
“Roof insurance can help after a covered event, but it works best when you already understand its limits and have a clear picture of your roof’s condition.”
Roof insurance is not a separate policy for most homeowners. It is part of your standard homeowners insurance, and it only responds under specific conditions. Many people discover the limits of that coverage only after a storm, when the adjuster explains why a claim was reduced or denied. Whitaker Roofing Company works with homeowners in Georgia, Alabama, and Tennessee who want a clearer picture of how roof insurance works before they need to file.
Understanding the basics can help you decide whether an inspection or repair now is smarter than waiting to see what the next storm does.
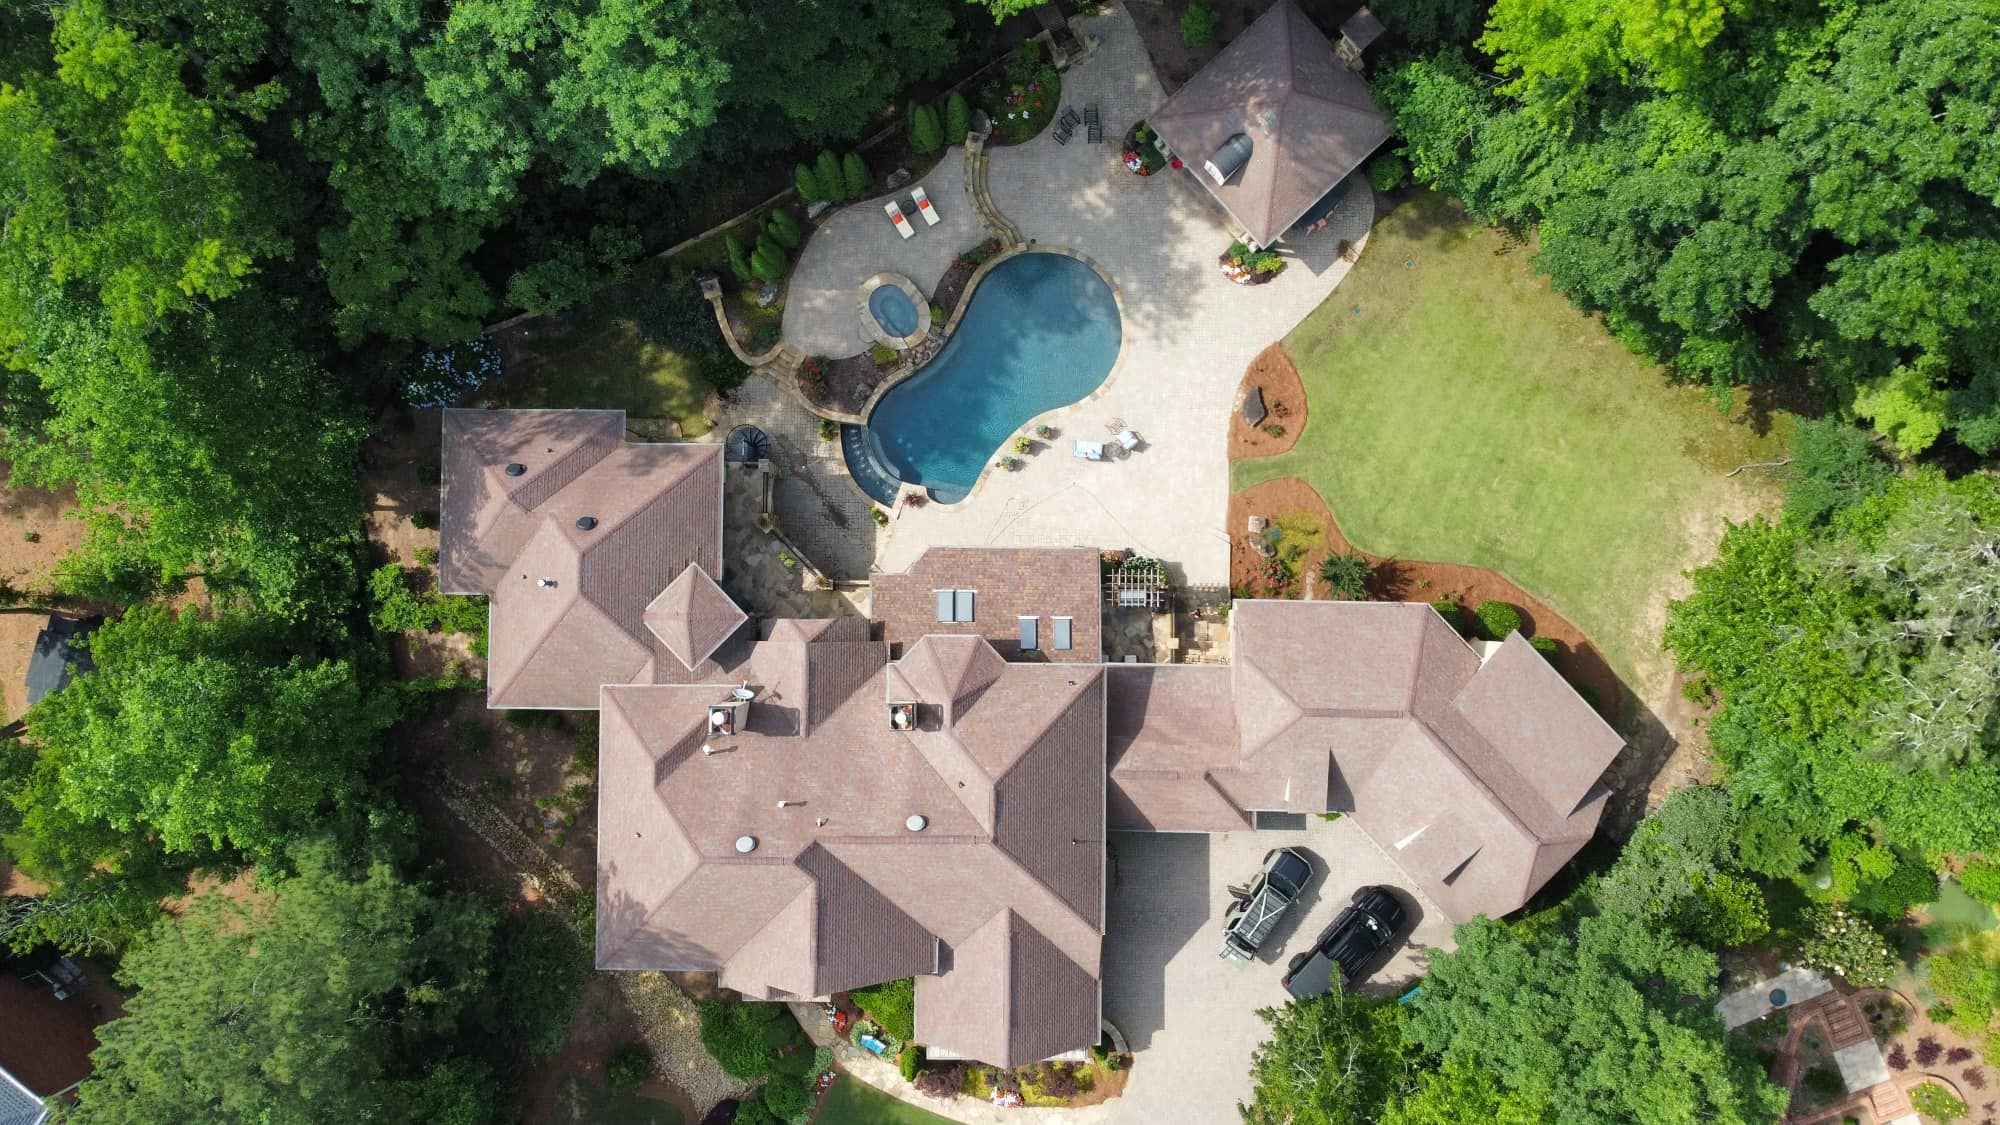
Most HO-3 policies cover the roof when damage comes from a named peril such as wind, hail, falling trees, or lightning. The policy is designed to restore the roof after an unexpected event. It is not designed to pay for the normal aging of materials.
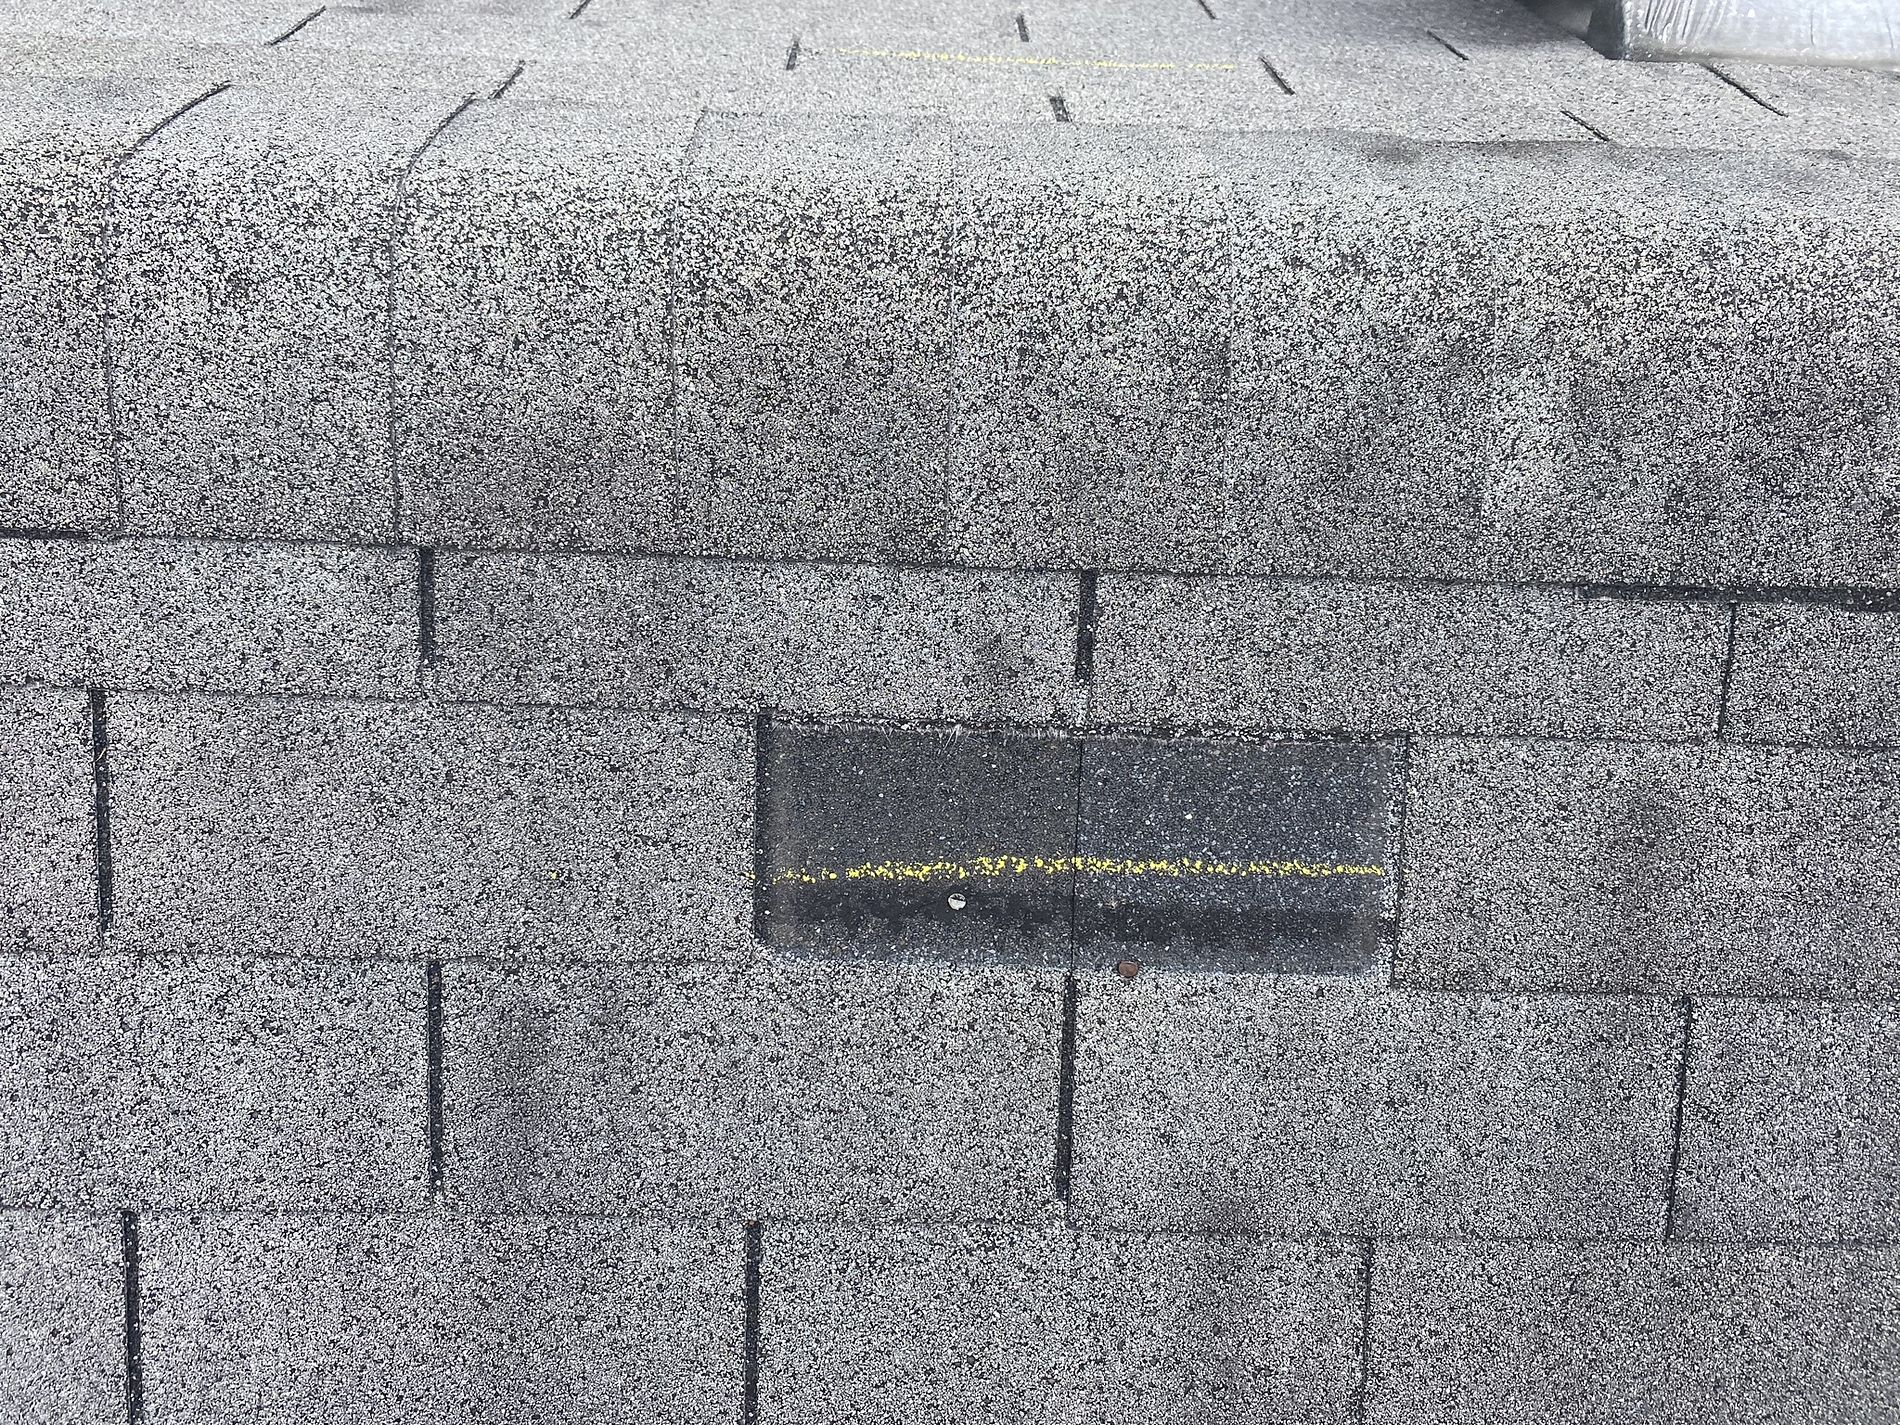
That distinction matters. Shingles that have lost granules from years of sun, flashings that have pulled away gradually, or leaks from long-term seal failure are usually treated as maintenance issues. A sudden hailstorm that bruises or cracks shingles can be covered if the damage is documented and the claim is filed promptly.
Whitaker Roofing Company sees both situations. A free inspection can help you understand whether current problems are more likely related to age and wear or to a recent weather event.
One of the most important details in roof insurance is whether your policy pays replacement cost value (RCV) or actual cash value (ACV).
Check your declarations page or talk with your agent to confirm which applies to your roof. The difference can be thousands of dollars. If your policy is ACV and your roof is older, a proactive repair or replacement may make more financial sense than relying on a future claim.
Your deductible is the amount you pay before insurance contributes. Some policies have a percentage deductible for wind or hail (for example, 1% or 2% of the dwelling coverage). On a higher-value home, that deductible can be large enough that a modest repair is not worth filing.
A free inspection and written estimate from Whitaker Roofing Company can help you compare the likely repair cost against your deductible. If the damage is below or near the deductible, paying for a targeted repair yourself and keeping the claim history clean may be the better path. If the damage is clearly above the deductible and tied to a covered event, documenting it thoroughly becomes more important.

Even with a strong policy, certain situations are commonly excluded or limited:
These exclusions are why regular attention matters. Clearing gutters in the fall, checking for lifted shingles after wind, and scheduling an occasional free inspection can reduce the chance that a future claim is denied for “lack of maintenance.”
You do not need an active claim to benefit from understanding your roof’s condition. Whitaker Roofing Company offers free inspections that include photos and a clear explanation of any issues found. That information is useful in several ways:
If damage is storm-related and you choose to file, we can provide additional documentation to help explain the scope. We also stand behind our own repair and replacement work with a 5-year workmanship guarantee on services, which is separate from whatever your insurance company pays.
Fall is a practical time to look at roof insurance while the weather is still manageable. Confirm:
If anything is unclear, your agent can explain the policy language. A free roof inspection at the same time gives you a current condition report to keep with your records.
Next steps
Roof insurance can help after a covered event, but it works best when you already understand its limits and have a clear picture of your roof’s condition. Whitaker Roofing Company provides free inspections and written estimates across Georgia, Alabama, and Tennessee so you can make informed decisions.
If you want to review your roof before storm season or after recent weather, call 678-252-6110 or visit wrcroofing.com. A no-cost look and an honest explanation can help you protect both your home and your insurance options.
ROOF INSURANCE Whitaker Roofing Company 31 October, 2026 Roof Insurance: What your policy actually covers — and what it leaves to you “Roof insurance can…
BIRMINGHAM ROOFING Whitaker Roofing Company 29 October 2026 Birmingham Roofing: Local service from our nearby Trussville office “Roofs in the Birmingham area face consistent challenges:…
ROOF WATER DAMAGE Whitaker Roofing Company 28 October 2026 Roof Water Damage: How fall storms turn small openings into bigger problems “Roof water damage is…
We’re confident we can help get your denied repair claims overturned.
Whitaker Roofing Company offers expert residential and commercial roofing services in Georgia, Tennessee, and Alabama. Specializing in roof inspections, repairs, and replacements, we ensure your roof’s durability and protection.
Trust our experienced team for quality workmanship and customer satisfaction. Contact us today to secure your roof’s longevity.